
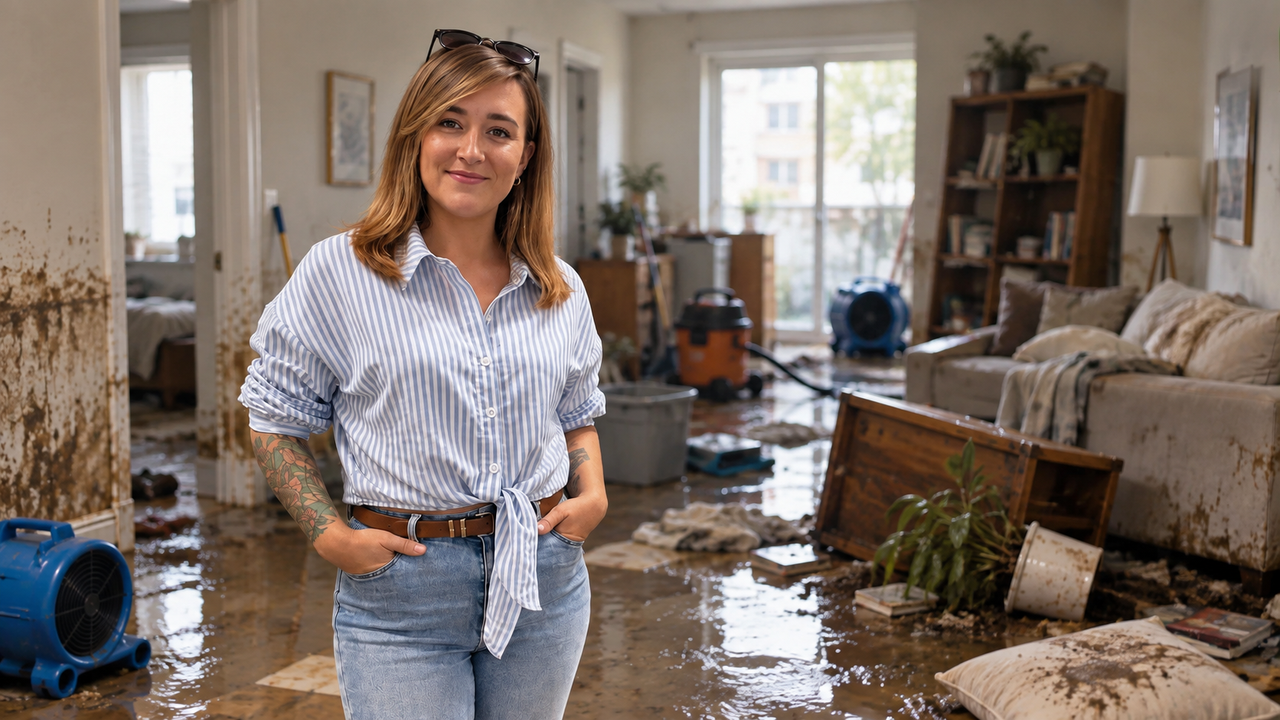
Insurance often only starts to interest us when something happens.
Fire.
Flooding.
Burglary.
Damaged equipment.
And then the question arises:
“Do I even have this insured?”
That's why, as part of Your Norway, we give a voice to people who work daily with the specific problems of Poles living in Norway.
The author of today's piece is Monika Roza – private customer advisor at Grind Forsikring.
And today, 16 September at 21:00, we also invite you to a live conversation on Radio Wataha.
Steve Joobs will talk with Monika about insurance in Norway without complicated language: what is really worth having, what we often do not understand and what mistakes only become apparent when a claim occurs.
During the live you will also be able to ask Monika your own question.
And now we hand over to her.
Text: Monika Roza, private customer advisor – Grind Forsikring
Insurance is not for having a policy. It should work when you really need it
When I talk with clients about insurance, I often see the same problem.
People know that they have "some kind of home insurance", but they do not always know what exactly is insured.
And here it's worth starting with the simplest thing:
husforsikring and innboforsikring are not the same.
The easiest way to remember it is like this:
husforsikring protects the building,
innboforsikring protects the things that are inside.
Of course each policy has its own terms, limits and exclusions, so you always need to check the specific contract.
The Norwegian forsikringsavtaleloven requires that before concluding an insurance contract, the client receive information, among other things, about the scope of coverage, main exclusions, the insured sum, their obligations and the rules for reporting a claim.
And that is exactly why you shouldn't compare insurance solely by price.
Husforsikring – you insure the building itself
If you are a homeowner, husforsikring concerns primarily the property itself.
That means elements such as:
roof,
walls,
floors,
installations,
elements permanently attached to the building,
built-in fixtures.
Grind Forsikring offers both standard husforsikring and a variant with extended coverage. The exact coverage depends on the chosen variant and the terms of the specific contract.
The simplest rule?
If you normally don't take something with you when you move, we usually consider it part of the building.
Innbo – in fact everything you would take with you when you move
Innboforsikring concerns your belongings.
Furniture.
Television.
Computer.
Clothes.
Bicycle.
Sports equipment.
Photos.
Electronics.
Everyday items.
Grind describes innbo as the items in the apartment that you can take with you when moving.
And here an important topic arises for Poles who rent apartments in Norway.
I'm renting an apartment. Do I need husforsikring?
Most often no.
If you rent an apartment or a house, the building belongs to the owner and the owner is responsible for the appropriate property insurance.
But the owner's building insurance does not automatically mean that your belongings are insured.
If there is a fire or major flooding and you lose:
laptop,
TV,
clothes,
furniture,
bicycle,
equipment,
children's belongings,
this is exactly where your contents insurance matters.
Practical information for tenants also clearly separates these two areas: the building and fixed elements are covered by the building insurance, whereas the tenant's own belongings require their own contents protection.
Is contents insurance mandatory?
There is no general legal rule that would require every tenant to have contents insurance.
But in my opinion the question should be asked differently:
Could I afford to replace everything I have in the apartment?
Only then do you start to add things up.
Bed.
Sofa.
Table.
TV.
Phones.
Computers.
Clothes.
Shoes.
Kitchen equipment.
Bicycle.
Children's belongings.
And suddenly it turns out that "I don't have anything expensive" can mean tens or even hundreds of thousands of kroner.
I have an apartment in a borettslag or sameie. Do I need building insurance?
In a typical borettslag or sameie, the insurance of the building itself is usually organized jointly.
In that case a single apartment owner usually does not buy a separate building insurance for the entire building.
But still needs their own contents insurance for their belongings.
Gjensidige describes this rule very clearly: the common insurance covers the building, including its internal elements, but not the resident's private contents.
If you are not sure, it is worth checking the documents of your sameie or borettslag.
What if the apartment is furnished by the owner?
Here we have two groups of items.
The owner may have:
furniture,
equipment,
fittings,
that belong to them.
You have your own belongings.
The owner's policy for their property does not replace your contents insurance.
Therefore, even if you rent a fully furnished apartment, it's still worth knowing how your own belongings are protected.
Take pictures of the apartment. Really.
It's one of the simplest things you can do.
And one of the most useful.
Once every few months, take your phone and walk through the apartment.
Record or photograph:
living room,
kitchen,
wardrobes,
electronic equipment,
tools,
bicycles,
sports equipment,
jewelry,
expensive items.
It's not about a professional photoshoot.
It's about the ability to later show:
"this is what my home looked like and these are the things I owned".
After a major fire you may be left with an empty apartment and try to recall everything you owned from memory.
This is much more difficult than it seems.
Gjensidige also recommends documenting particularly valuable items, because in the event of a major loss it can be very difficult to accurately reconstruct your entire estate from memory.
Receipts - throw away or keep?
For more important purchases, I recommend keeping them.
Especially with:
expensive electronics,
computers,
bicycles,
jewelry,
photographic equipment,
expensive tools,
collectible items,
higher-value items.
You don't have to keep the box from every kettle for ten years.
But a photo of the receipt or invoice can make things much easier later.
You can create a simple cloud folder:
HOME / INSURANCE
and put there:
photos of the apartment,
bills,
serial numbers,
invoices,
photos of particularly valuable items.
When reporting a claim, the insured person is obliged to provide available information and documents necessary to determine liability and the amount of compensation. The forsikringsavtaleloven also says the same.
The better you can document what you owned, the easier it will be later to carry out the claims settlement process.
Don't guess when taking out a policy
This is also very important.
If an insurance company asks you for information that is relevant to the risk, answer truthfully and accurately.
The law requires the client to provide correct and complete information in response to questions concerning risk. If it later turns out that material information was incorrect or withheld, this may affect the compensation.
Therefore, if you don't understand something:
ask.
Don't click "yes" because you think that's how it should be.
An advisor is there to explain what the question means and how it affects your coverage.
Price is not everything
You can have two policies that cost about the same.
And yet the differences between them can be very large.
Check:
what is insured,
up to what amount,
what the deductible is,
what the policy does not cover,
what additional conditions there are,
what obligations you have as a customer.
Norwegian law requires that the standard information about an insurance product include, among other things, the main risks, the scope, significant exclusions, the client's obligations and the procedure for handling a claim.
These are things more important than a difference of tens of kroner per month.
What about flooding, landslides or another natural disaster?
Norway has a special solution regarding naturskade.
If an item in Norway is insured against fire, the law also provides protection against certain natural hazards, such as landslides, storms, floods, storm surges, tsunamis, earthquakes or other listed events, provided the damage is not covered by another insurance.
This is a good example showing that insurance in Norway is not based solely on the document from the company – some rules also arise directly from the law.
My simplest advice
Once a year, do a review of your insurance.
Ask yourself a few simple questions:
Do I still live at the same address?
Have I bought anything valuable?
Has a child joined the family?
Has my family situation changed?
Am I renting out part of the house?
Do I have a new bike, equipment or electronics?
Does my current insurance still match the way I actually live?
Insurance shouldn't be a document purchased five years ago and forgotten in a drawer.
It should change together with your life.
House or contents – remember one rule
If I had to leave you with only one simple image, I would say:
turn your home upside down.
What remains attached to the building, associate with house insurance.
What falls out of the home, in broad terms, is contents.
This is not a legal definition and you always have to read the specific policy terms.
But as a simple way to remember the difference, it works very well.
And most importantly:
do not wait to check your policy until the day something happens.
By then it is already too late to change the scope of coverage.
Monika Roza
Private Advisor – Grind Forsikring
Phone: 925 07 059
E-mail: mr@grindforsikring.no
Today at 21:00 – Monika Roza live on Radio Wataha
The article gives the basics.
But insurance quickly starts to depend on the specific situation.
Therefore today, 16 September at 21:00, Steve Joobs invites you to a live conversation with Monika Roza.
We'll discuss, among other things:
whether a tenant really needs contents insurance,
what is the difference between house and contents,
what a homeowner should have,
what about an apartment in a borettslag or sameie,
which items are worth documenting additionally,
why photos and receipts can be very important,
what to look for in the policy terms,
what Poles most often do not know about their insurance,
whether the cheapest offer is really the most advantageous,
which questions are worth asking the advisor before we sign the contract.
And most importantly: you will be able to ask Monika your own questions live.
Radio Wataha
16.09.2026
21:00
Steve Joobs talks with Monika Roza